Reading the Signals in Employment, Vacancy and Earnings Data
No single figure tells the full story of the British labour market. Taken together, employment rates, inactivity levels, payroll counts, vacancy numbers and earnings data form a more honest picture – though even that picture has limits.
Employment and Inactivity
The Office for National Statistics distinguishes between unemployment – actively seeking work – and economic inactivity, which covers those neither working nor looking. Since 2020, inactivity has risen sharply among working-age adults, driven largely by long-term sickness. An employment rate that holds steady while inactivity climbs signals something quite different from genuine labour market strength.
Vacancies and Recruitment Pressure
Vacancy figures peaked at over 1.3 million in 2022 before falling steadily. High vacancy counts indicate recruitment difficulty, but not necessarily wage growth or productivity gains. Persistent shortfalls in specific sectors – health, logistics, construction – reflect structural gaps rather than cyclical hiring surges.
Earnings and Living-Cost Context
Nominal wage growth above 7% in 2023 looked strong until measured against inflation running at similar or higher levels. Real earnings – adjusted for price changes – remained flat or negative for much of that period. Single-month pay figures rarely capture this adequately, which is why trend data across rolling quarters provides a more reliable baseline.
Why Opportunity Looks Different Across Regions and Nations
Geography shapes employment outcomes in ways that aggregate national figures rarely capture. A vacancy rate or median salary reported at UK level conceals enormous variation between places with fundamentally different industrial bases, housing markets and public sector footprints.
London Versus the Rest
Median full-time earnings in London run roughly 20% above the national figure, but once private rental costs are applied, that premium erodes sharply for many occupational groups. The capital's labour market is concentrated in finance, professional services and tech, which inflates average wages while leaving lower-paid workers in a worse position relative to costs than counterparts in, say, Leeds or Cardiff.
National Differences Across the UK
Public sector employment accounts for a significantly higher share of jobs in Wales, Northern Ireland and parts of Scotland than in South East England. That concentration affects both wage floors and vacancy patterns. Northern Ireland's labour market also reflects cross-border dynamics with the Republic that have no equivalent elsewhere in the UK.
The Changing Geography of Work
Remote and hybrid working has allowed some professionals to access London-level salaries from lower-cost locations. That shift is real but uneven. Place-based industries – construction, social care, hospitality – cannot be performed remotely, meaning the geographic redistribution of opportunity remains partial rather than structural.
Where Skills Shortages and Future Demand Are Taking Shape
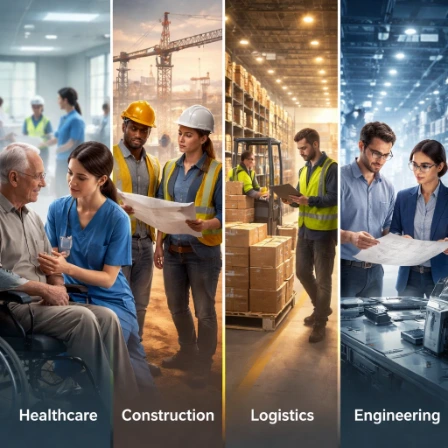
Recruitment difficulties are not spread evenly across the economy. Certain sectors have faced persistent, structural shortages that pre-date the pandemic and show little sign of easing.
Sectors Under the Most Pressure
Health and social care, construction, logistics, and engineering consistently record the highest vacancy-to-unemployed-worker ratios in ONS data. Hospitality struggles with high turnover rather than absolute scarcity. Digital roles, particularly in cybersecurity and data engineering, face a qualification gap that training pipelines have not yet closed.
An Ageing Population Raising Workforce Demand
Demographic pressure is sharpening shortages in care-related occupations. With over-65s projected to represent nearly a quarter of the UK population by 2043, demand for care workers is rising faster than recruitment can match. An ageing workforce within the sector itself compounds the problem.
Technology Reshaping Rather Than Replacing
Automation is changing task composition within jobs rather than eliminating roles wholesale. Radiographers now spend less time on image review; warehouse operatives manage automated systems rather than replace them. Skills requirements are shifting, not disappearing.
Reading Durable Trends in the Data
Sustained vacancy levels over 12–18 months, combined with wage growth above sector averages, typically indicate structural rather than cyclical demand. Where both signals align, as in adult social care and civil engineering, labour market data suggests durable opportunity rather than a temporary hiring spike.
The Strongest Trends Are The Ones Confirmed Over Time
Single data points rarely tell the full story. Vacancy counts spike and fall with seasonal hiring; payroll figures shift after Budget announcements; redundancy numbers can reflect one large employer rather than a broad sectoral retreat. What gives labour market evidence its real weight is consistency across multiple indicators, sustained over several quarters, and visible across different geographies. Regional disparities between London and the rest of the UK, persistent shortages in health and social care driven by an ageing population, the uneven spread of automation across occupations, and the gradual normalisation of hybrid working are all reshaping opportunity – but not uniformly. Scotland, Wales, Northern Ireland and English regions each face distinct pressures. Reading these patterns carefully, rather than anchoring on headline salary averages or a single month's employment rate, is what separates a genuine structural shift from noise.